The future of travel commerce
Retailing, personalisation and dynamic offers, and how travel companies are becoming platforms.
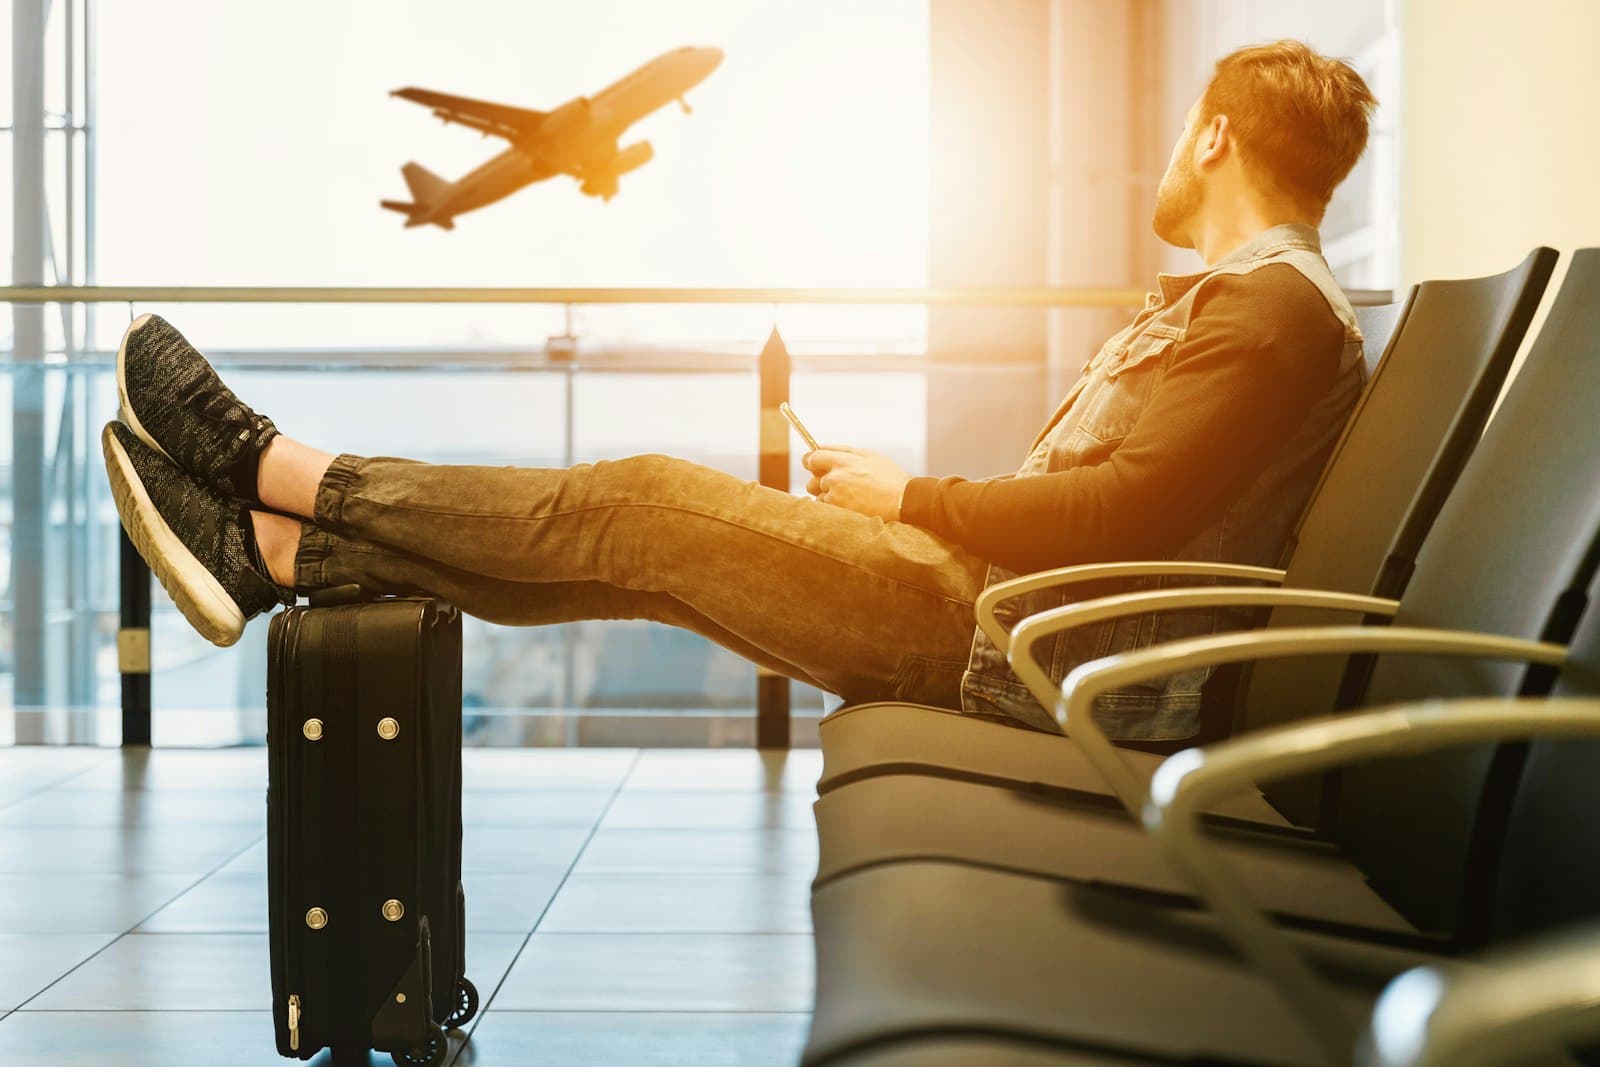
For twenty years, travel commerce has been a distribution problem dressed up as a retail one. The winners of the next decade will be the operators who invert that: retail first, distribution second, everything else in service of the offer.
The offer is the product now
In the old model, inventory was king. If you had the room or the seat, you could sell it. That world is over. Every operator has inventory. The scarce good is the ability to compose an offer, the room, the transfer, the experience, the price, at the moment the traveler is ready to buy.
Dynamic offer construction is not a fancy pricing engine. It is a full-stack capability: identity, intent, inventory, price and merchandising all in one loop, running in milliseconds, against real-time supplier feeds.
Three architectural moves worth making
- Consolidate the middle layer. Most operators today buy shop, price and book from three different vendors. The seam between them is where most of the conversion is lost.
- Treat mobile as the primary surface. It already is. The desktop-first codebase is a legacy artifact, and it is the reason your peak-season conversion has been flat for three years.
- Own the offer engine. If a supplier writes it for you, they get to price you against your own customers.
“We spent a decade optimising the funnel. We should have been rebuilding the shelf.”
The organisational shift
The interesting thing is that this is not primarily a technology shift. It is an organisational one. The commerce team, the product team and the revenue team have to sit in the same room and share a single set of metrics.
The operators making the change earliest are already seeing double-digit conversion lift and, more importantly, a repeatable engine for the next round of it. The rest are still shipping A/B tests on a checkout that will not survive the next platform migration.
Frequently asked
01What is changing in how travel is actually booked?
The search step is moving away from the supplier's own site. Travellers increasingly arrive having already narrowed their choice somewhere else, which means the booking path has to be fast, trustworthy and capable of holding inventory accurately at the moment they commit. The competitive ground is shifting from discovery to execution.
02Why is inventory accuracy such a persistent problem?
Because availability is distributed across suppliers who each update on their own schedule, and the traveller experiences any disagreement as a failed booking. The platforms that handle this well treat supplier responses as untrusted input, normalise aggressively at the edge, and design what happens when a supplier is slow rather than assuming it will not be.
03Does personalisation still pay back?
Where it reduces effort, yes. Remembering a traveller's context so they do not re-enter it is reliably worth building. Inferring intent from thin signals usually is not, and in travel it is especially visible when it is wrong. We would rather spend the budget on making the booking path faster.
04What should a travel business fix first?
Whatever is costing bookings at the point of commitment. In most of the estates we see that is latency or inventory disagreement on the final steps, not the quality of search results earlier in the journey. It is also the easiest thing to measure before and after.